
06.11.2026
New car market declines 14.3% vs last year, but up 14.7% against September 2026
- SUVs continue to dominate Indian passenger vehicle sales
- Petrol makes up just over half of fuel mix, but diversification continues
India’s passenger vehicle market registered 511.7K units in October 2026, a 14.3% YoY decline from 596.9K units in October 2025. The contraction reflects the exceptionally high festive-season base of the previous year and softer retail momentum across several volume-driven segments.
On a month-on-month basis, registrations increased by 14.7%, rising from 446.0K units in September 2026 to 511.7K units in October 2026. The sequential improvement was supported by festive purchases, higher dealership footfall, attractive promotional offers and sustained demand across key passenger vehicle categories.
Ravi Bhatia, President at JATO Dynamics India, said: "The Indian passenger vehicle market recorded 511.7K registrations in October 2026, delivering strong month-on-month growth despite a decline compared with the exceptionally high base recorded in October 2025. Festive demand, continued SUV preference, healthy CNG adoption, and broad-based registrations across key states and cities supported overall market activity."
SUVs drive India's October 2026 car sales
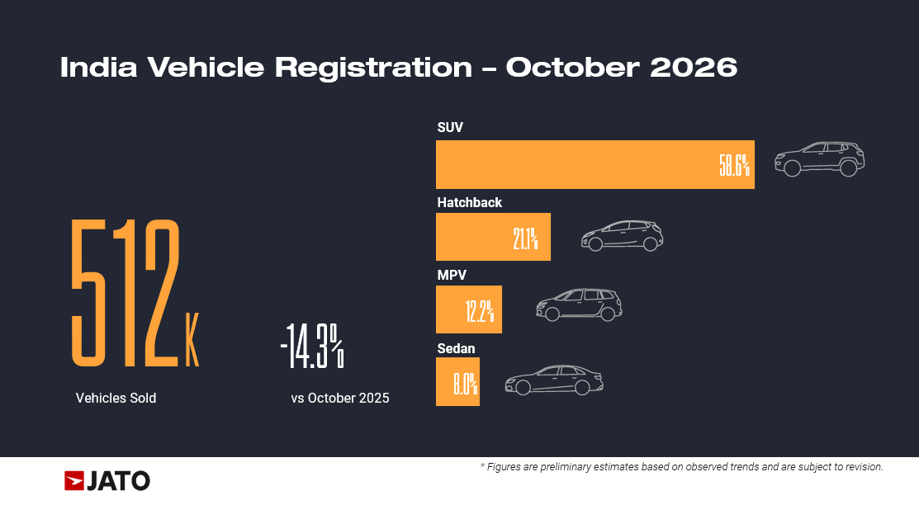
The passenger vehicle market remained strongly SUV-oriented in October 2026. SUVs accounted for 58.6% of total registrations, reinforcing their leadership as the dominant body style. Consumers continue to favour vehicles offering greater practicality, higher seating positions, enhanced features and improved road presence.
Hatchbacks contributed 21.1% of registrations, remaining an important segment for urban and value-conscious buyers. MPVs accounted for 12.2% of volumes, supported by family and commercial usage demand.
Sedans represented 8.0% of registrations, with demand concentrated around a few key nameplates, particularly the Maruti Suzuki Dzire. The segment mix demonstrates the continued shift of Indian consumers toward SUV ownership, with the category nearing three-fifths of all passenger vehicle registrations.
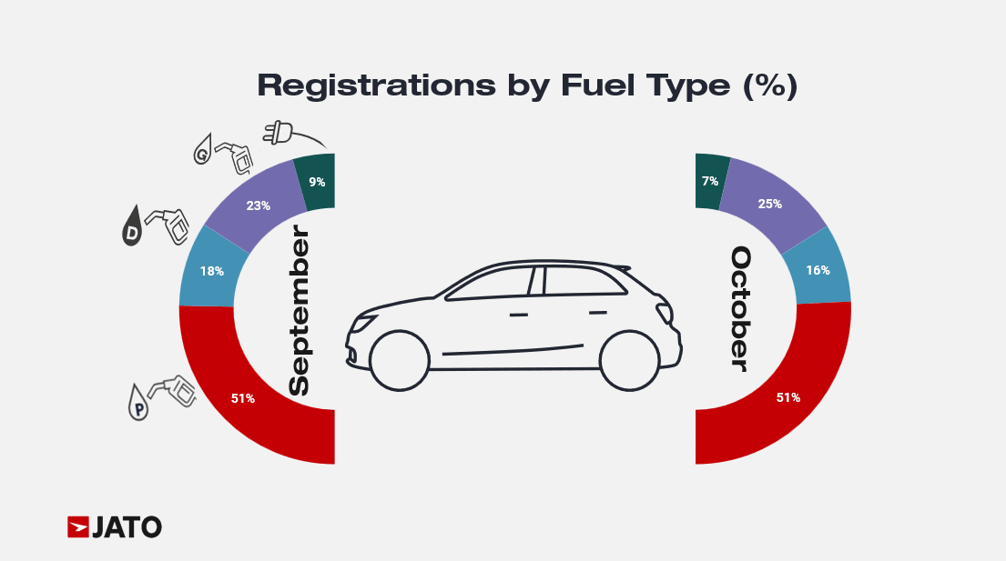
Conventional powertrains continued to dominate in October 2026. Petrol vehicles accounted for 51% of total registrations, maintaining their position as the most preferred fuel type thanks to widespread availability and lower ownership complexity.
CNG vehicles represented 25% of registrations, reflecting sustained demand for economical mobility and lower running costs. Diesel vehicles contributed 16%, with demand found primarily in SUVs and utility vehicles.
Electric vehicles accounted for 7% of total registrations, supported by increasing model availability, expanding charging infrastructure and growing consumer awareness. The fuel mix highlights a gradual transition toward alternative fuel technologies, while petrol remains the dominant powertrain choice.
India’s October 2026 passenger vehicle manufacturer performance
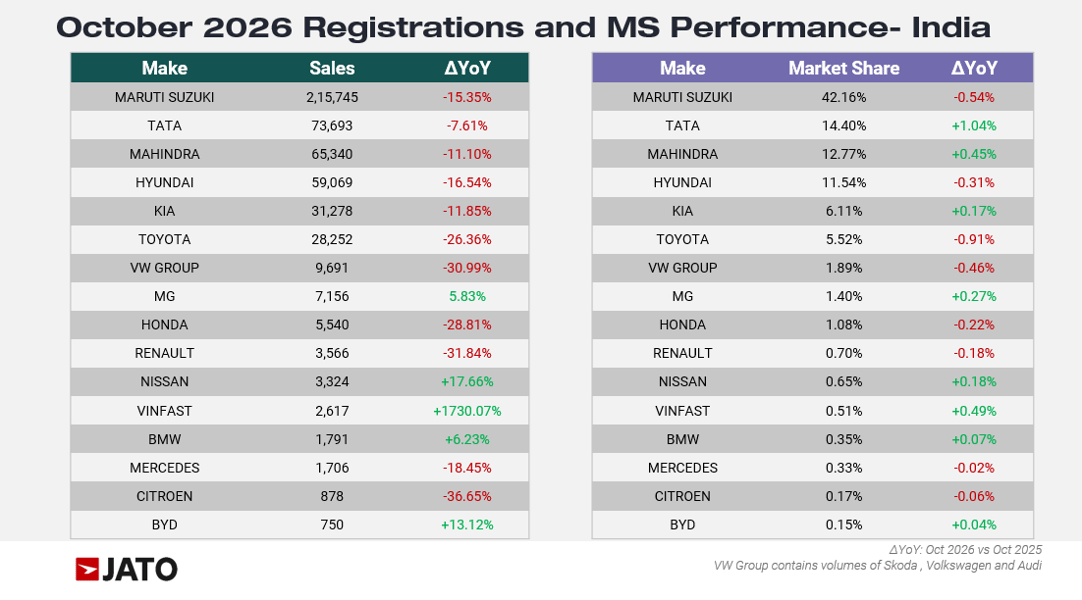
Maruti Suzuki retained its leadership position with a 42.2% market share, accounting for more than two-fifths of all passenger vehicle registrations. Its share declined marginally by 0.54 percentage points YoY, reflecting increasing competitive pressure across segments.
Tata Motors was the strongest market-share gainer among major OEMs, increasing its share to 14.4%, a gain of 1.04 percentage points YoY, supported by strong performance from key SUV models. Mahindra strengthened its presence with a 12.8% share (+0.45 percentage points YoY), driven by continued demand across its utility vehicle and SUV portfolio.
Hyundai held an 11.5% share, down 0.31 percentage points YoY, while Kia increased its share to 6.1%, supported by strong SUV demand. Toyota accounted for 5.5% of registrations.
MG Motor, Nissan, VinFast, BMW and BYD all posted market share gains compared with the previous year. Among newer entrants, VinFast recorded one of the largest increases at +0.49 percentage points YoY. Overall, the competitive landscape remained led by Maruti Suzuki, while Tata Motors and Mahindra strengthened their positions through sustained growth in utility and SUV segments.
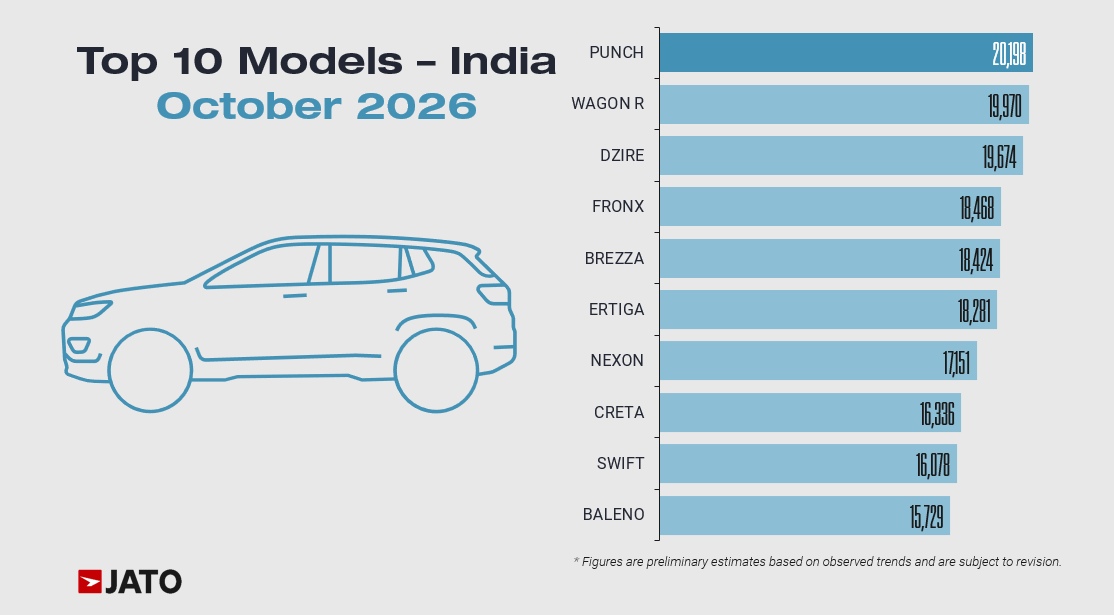
At the model level, the Tata Punch was India’s best-selling passenger vehicle with registrations of 20,198 units. The Maruti Suzuki WagonR followed closely with 19,970 units, while the Dzire recorded 19,674 units, maintaining its strong position in the sedan segment.
The Maruti Suzuki Fronx registered 18,468 units, narrowly ahead of the Brezza at 18,424 units. The Ertiga continued to lead the MPV segment with 18,281 registrations. Other strong performers included the Tata Nexon (17,151 units), Hyundai Creta (16,336 units), Maruti Suzuki Swift (16,078 units) and Baleno (15,729 units).
The rankings continue to highlight the dominance of SUVs, while also showing sustained demand for hatchbacks, MPVs and compact sedans.
Delhi, Maharashtra and Gujarat lead regional demand
Delhi was the largest city-level market with approximately 21.0K registrations, followed by Pune with 16.7K and Bengaluru with 15.8K. Other major markets included Mumbai, Hyderabad, Ahmedabad, Jaipur, Gurugram, Chennai and Lucknow.
At the state level, Maharashtra remained India’s largest market with approximately 66.5K registrations, followed by Gujarat with 55.2K and Uttar Pradesh with 51.1K. Karnataka, Haryana, Rajasthan and Tamil Nadu also ranked among the leading contributors, with Delhi, Madhya Pradesh and Kerala completing the top ten.
Urban markets contributed the largest share of registrations in October 2026 at 294.2K units, despite an 18.0% YoY decline. Metro markets contributed 133.1K units (-8.3% YoY), while rural markets recorded 84.4K registrations (-9.2% YoY). All classifications declined against the high festive base of October 2025, but urban markets remained the primary demand centres.
Dealer inventory averaged 30-35 days of stock in October 2026, supported by improved supply availability and proactive stocking ahead of the festive season. Despite strong retail activity, levels remained within comfortable industry norms, indicating a balanced demand-supply environment.
Outlook
Overall, the passenger vehicle industry remains supported by strong consumer interest in SUVs, expanding product portfolios, increasing fuel diversification and broad-based regional demand, positioning the market for stable performance in the coming months.
-ENDS-
For full rankings, detailed analysis or media enquiries please contact Laura Cameron: laura.cameron@jato.com
About JATO
Founded in 1984, JATO Dynamics is the world’s leading provider of automotive market intelligence. Operating across more than 50 markets worldwide, JATO delivers accurate data and insights on vehicle specifications, pricing, sales and registrations, powering data-driven decisions across the global automotive industry.
Trusted by manufacturers, retailers, leasing and financial services organisations, JATO’s insights support everything from vehicle comparison and digital retail optimisation to the identification of regional and global market trends.