

New Delhi, 7th October 2026 – India’s passenger vehicle market saw excellent growth in September 2026, with registrations increasing by 31.0% YoY to 423.4K units, compared to 323.3K units in September 2025. This sharp growth was driven by festive season buying, continued strength in SUV demand, improving consumer confidence, and healthy availability across leading models and brands.
Looking at a month-on-month basis, registrations increased by 0.9%, rising from 419.7K units in August 2026 to 423.4K units in September 2026. The positive sequential growth indicates sustained retail momentum despite an already strong August base, highlighting robust demand conditions ahead of the festive season.
Ravi Bhatia, President at JATO Dynamics India, said: "The passenger vehicle industry in India remains on a healthy trajectory, with September 2026 again showing significant growth. This has been supported by favourable consumer sentiment, expanding product portfolios, improving technology adoption, and balanced demand across urban, metro, and rural markets."
SUVs drive India's September 2026 PV sales forward
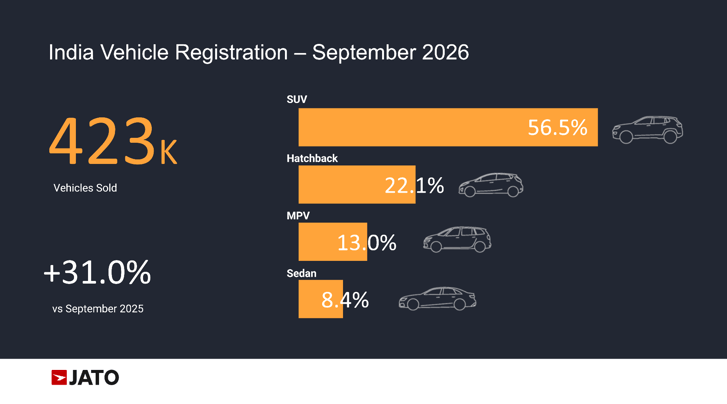
The passenger vehicle market remained heavily SUV-oriented during September 2026. SUVs accounted for 56.5% of total registrations, reinforcing their position as the dominant body style in India. Consumer preference continues to shift toward vehicles offering higher ground clearance, enhanced features, and greater practicality.
Hatchbacks contributed 22.1% of registrations, maintaining relevance among urban and first-time buyers. MPVs accounted for 13% of volumes, supported by strong demand from family-oriented buyers and fleet operators.
Sedans represented 8.4% of total registrations, with the segment continuing to be driven largely by models such as the Dzire. The segment mix clearly demonstrates the ongoing migration of Indian consumers toward SUV ownership, with the category now contributing well over half of all passenger vehicle registrations.
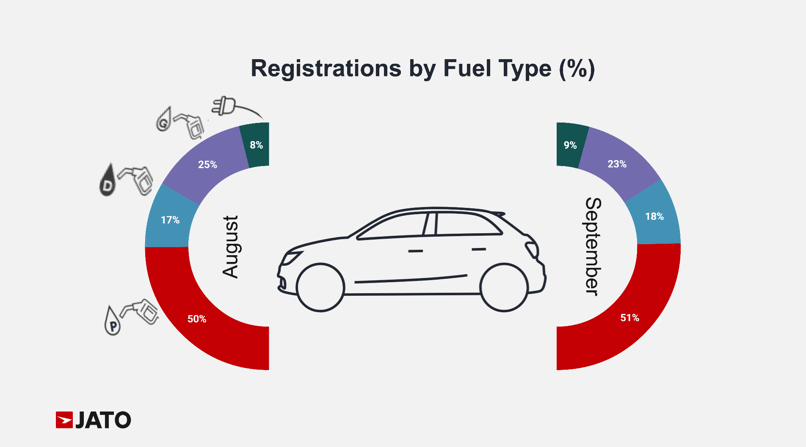
The fuel mix remained diversified in September 2026, although traditional powertrains continued to dominate overall demand. Petrol vehicles accounted for 51% of total registrations, maintaining their position as the leading fuel choice due to widespread availability and lower acquisition costs.
CNG vehicles represented 23% of registrations, reflecting growing consumer preference for economical mobility solutions amid fuel cost considerations. Diesel vehicles contributed 18%, supported primarily by SUVs and utility vehicles where higher torque and long-distance capability remain important factors.
Electric vehicles accounted for 9% of total registrations, showcasing continued growth in EV adoption and an expanding range of electric offerings across the market The fuel mix highlights the gradual evolution of India's passenger vehicle market toward alternative fuel technologies while petrol continues to retain a dominant presence.
India's September 2026 passenger vehicle manufacturer performance
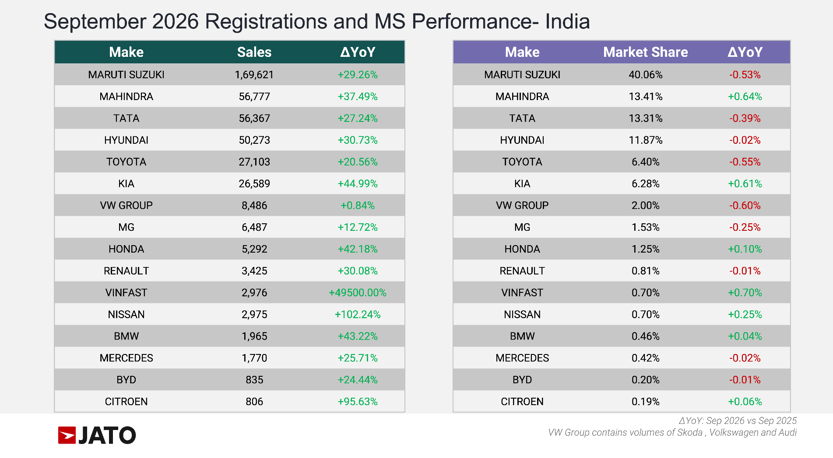
Maruti Suzuki retained its leadership position with a 40.1% market share, accounting for over two-fifths of all passenger vehicle registrations during the month. Although volumes grew strongly by 29.3% YoY, market share declined marginally by 0.53 percentage points, reflecting increasing competition.
Mahindra continued to strengthen its position in the market, achieving a 13.4% share and recording the highest market share gain among major OEMs at +0.64 percentage points YoY. The company’s sustained growth was supported by strong customer demand across its utility vehicle and SUV portfolio.
Kia emerged as another notable gainer, increasing its market share to 6.3%, supported by strong growth across its SUV line-up. Overall, the competitive landscape continued to be dominated by Maruti Suzuki, while Mahindra and Kia strengthened their positions through sustained growth in the SUV segment.
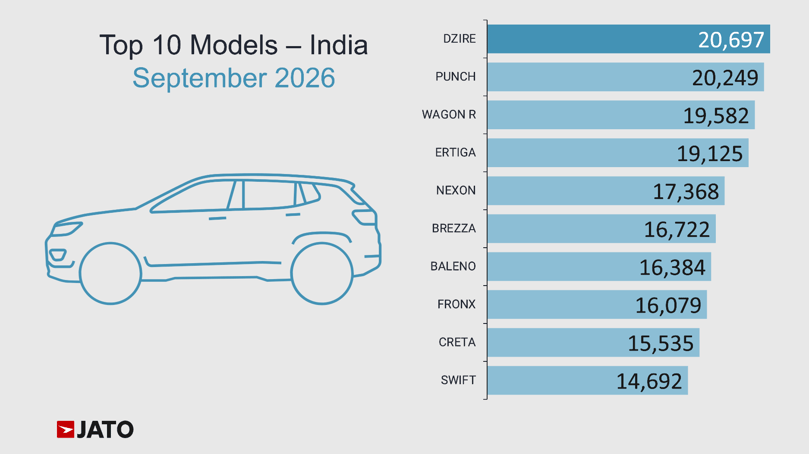
At the model level, Maruti Suzuki's Dzire remained India's best-selling passenger vehicle with registrations of 20,697 units, reaffirming its leadership within the sedan segment. The Tata Punch followed closely with 20,249 units, continuing its strong performance within the compact SUV category.
Maruti Suzuki's Wagon R registered 19,582 units, while Ertiga recorded 19,125 units, maintaining its leadership position in the MPV segment. Tata's Nexon achieved 17,368 registrations, reflecting continued strength in the compact SUV market.
Overall, the passenger vehicle industry remains on a healthy growth trajectory, supported by favourable consumer sentiment, expanding product portfolios, improving technology adoption, and balanced demand across urban, metro, and rural markets.
Data source: JATO vehicle registration data as of 1 October 2026. YoY comparison with September 2025.
For full rankings, detailed analysis or media enquiries please contact Laura Cameron: laura.cameron@jato.com
Notes to Editor:
About JATO
Founded in 1984, JATO Dynamics is the world’s leading provider of automotive market intelligence. Operating across more than 50 markets worldwide, JATO delivers accurate data and insights on vehicle specifications, pricing, sales and registrations, powering data-driven decisions across the global automotive industry.
Trusted by manufacturers, retailers, leasing and financial services organisations, JATO’s insights support everything from vehicle comparison and digital retail optimisation to the identification of regional and global market trends.
Visit JATO at www.jato.com for more information.